The first question
What do I need to do before my enrollment window closes, and what happens if I get it wrong? Timing first, plans second.
Every Medicare enrollment window, in one place 970.505.9652
Compare Plans
Book a Review
Turning 65
Every one of those envelopes is guessing about you. None of them know your medications, your doses, or your doctors. Start with the part that decides most of the cost, and let the plan names come last.
Optional — we are glad to do this part for you
Some people want to look before they talk to anybody, and that is a reasonable way to go about it. So here is the same tool we use when we sit down with you. Put in your ZIP code and what you take, and it will do the arithmetic.
There is no charge either way. Handing us the list is the shorter road, and it is the one most people take.
Living in Wyoming? Wyoming plans sit on a separate version of the tool. If that is where you are, start here instead.
Open the Wyoming plan toolSo run it if you like the look of it. Then bring us what you got, and we will check the parts a form cannot.
The seven months that matter
Your Initial Enrollment Period is seven months long: the three months before the month you turn 65, your birthday month itself, and the three months after. Every month inside it is penalty-free. They are not equal, though, because the month you sign up decides the day your coverage starts.
| When | What to do | When coverage would start |
|---|---|---|
| 4 to 6 months before | If you have coverage through work, ask HR one question: is this creditable coverage for Medicare? Get the answer in writing. | Nothing starts yet. That letter is the document that defeats a penalty years from now. |
| 3 months before your birthday month | Your window opens. Sign up for Part A and Part B through Social Security, unless you are keeping creditable coverage through work. | The first day of your birthday month. No gap. |
| 2 months before | Sit down with your medication list and your doctors and compare the actual plans. This is the work that decides your year. | Still the first day of your birthday month. |
| 1 month before | Enroll in the plan you chose. This is the last month that gets you coverage on day one. | Still the first day of your birthday month. |
| Your birthday month | Still allowed and still penalty-free. Nothing has gone wrong. | The first day of the following month, so you will be without Medicare for part of a month. |
| 1, 2 or 3 months after | The window is open and there is still no penalty. Later is worse only because the gap gets longer. | The first day of the month after you sign up. |
| Month 8 and beyond | The window has closed. Call us the same week rather than waiting. | You may have to wait for the General Enrollment Period, January 1 to March 31, and the Part B penalty clock has started. |
What do I need to do before my enrollment window closes, and what happens if I get it wrong? Timing first, plans second.
Every Medicare enrollment window, in one placeSeven months, not one
Medicare gives you seven months to enroll in Part A and Part B: the three months before the month you turn 65, the month you turn 65, and the three months after. That is the whole window.
It is not October to December, which is a different period for people who already have Medicare, and it does not extend because you were busy or because the mail was confusing.
The three months before your birthday month are the ones worth using, because they are the only ones that start your coverage with no gap.
What a late enrollment penalty actually costsA real quirk worth knowing
Medicare treats a first-of-the-month birthday as though you turned 65 the month before. Premium-free Part A then starts the month before you turn 65 rather than the month you do.
It is a small thing that changes every date on your calendar by one, and it is the kind of detail a mailer will never mention. If your birthday is the 1st, say so when we talk and we will work your dates from there.
The assumption that costs people money
If you are already receiving Social Security when you turn 65, you are enrolled in Part A automatically and the welcome package arrives about three months before coverage begins.
If you are not claiming Social Security yet, which is now most people at 65, nothing arrives and nothing is scheduled. No letter, no card, no reminder. You have to apply through Social Security yourself, and the seven-month window runs whether or not anyone tells you it started.
Rather just ask someone
Bring the card, the letter, or just the question. We will read it with you, and there is no charge for the conversation.
Two clocks nobody mentions
Both are anchored to Part B rather than to your birthday, and both are easy to miss because no letter announces them. One of them never comes back.
About all that mail
A premium printed on a postcard tells you almost nothing about what your year will cost, because it says nothing about the drugs you take or the doctors you see. Bring us the actual list and the answer stops being generic.
Permission to ignore most of it
The volume of mail and phone calls is designed to feel like a deadline. Almost none of it is. It helps to know which pressure is real and which is manufactured, so here is the short version.
What people say
I have referred many patients from the clinic where I work who either lack insurance coverage or do not have adequate benefits, and Juan Carpenter has consistently made a meaningful difference in their lives.
We appreciate Juan's expertise and pleasant manner while exploring all the details of Medicare coverage.
Juan was very informative and extremely helpful.
Juan is great to work with. Very knowledgeable, works with you to find the best possible plan! Highly recommend!
Why Haven
Whether something is covered is the easy question. What a plan does with it after that — the tier, the network, the rule attached to it — is where the year gets expensive, and that detail is a pharmacist's daily work.
Haven was started by the pharmacists at Good Day Pharmacy. So you can check us out before you ever pick up the phone. Not many people in this business can say that.
It is fair to wonder. We do not. If the best plan for your medications means filling somewhere else, we will tell you so. The only time a pharmacy comes into it is if you ask us to keep yours.
A plan can list your medication and still cost you much more than the plan next to it. It comes down to tiers, limits, and prior authorizations. That is a pharmacist's daily work, and it is where most of the money hides.
Pharmacists are the ones who tell you what your prescription costs today. We did that for years. Then we got licensed, so the hard conversation could happen in October instead of January.
Not a vague promise that most plans cover most doctors. We look up your specific physicians and specialists in front of you, before any plan gets named.
Greeley, Fort Collins, Loveland, Windsor and the towns around them are where we live. We also reach Grand Junction, Palisade and Colorado Springs, and we are licensed in 25 states, so a move or a parent out of state is no trouble.
Not a referral pipeline and not a pharmacy preference. A better introduction. When a pharmacist calls and says your name and how long they have known you, the conversation starts with a person who has a history instead of a lead off a list. That is most of what the pharmacy side is worth to you.
Letters arrive. Drugs move tiers. A prior authorization gets denied. When that happens you call the same person who set your plan up, and we help you read it. That is the part most people never get.
Ask us anything
In one of the three months before the month you turn 65. That is the only part of your window that starts your coverage with no gap, on the first day of your birthday month.
You can still enroll during your birthday month or the three months after with no penalty, but coverage then starts the first of the following month and you go uncovered for part of a month.
Seven months. It runs from three months before the month you turn 65, through your birthday month, to three months after it. Every month inside that window is penalty-free.
Only if you are already receiving Social Security benefits, in which case Part A is automatic and the welcome package arrives about three months before coverage starts. If you have not claimed Social Security yet, nothing happens automatically and nothing will be mailed to remind you.
You apply through Social Security yourself, and the seven-month window runs either way.
Yes, by one month. Medicare treats a first-of-the-month birthday as though you turned 65 the month before, so premium-free Part A starts the month before you turn 65. Every date on your calendar shifts a month earlier.
Tell us your birthday is the 1st and we will work your dates from there.
You may have to wait for the General Enrollment Period, January 1 to March 31, and coverage then starts the first of the month after you sign up. A late enrollment penalty may also apply, and the Part B penalty is permanent.
If your window has already closed, call this week rather than waiting for January, because there are situations that open a Special Enrollment Period instead.
It depends on your employer's size, and the difference matters. At 20 or more employees you can usually delay Part B while that coverage lasts, with no penalty later.
Under 20 employees, the group plan may not pay correctly without both Part A and Part B, which turns it from a penalty question into a coverage gap. Ask HR in writing whether your plan is creditable coverage for Medicare, and keep the answer.
No. Not one of those envelopes requires a response, and none of them is an offer that expires.
They come from insurance companies, not from Medicare, and they are addressed to a ZIP code rather than to you, which is why they lead with a premium instead of anything about your prescriptions or your doctors.
No, and you should hang up. Medicare does not cold-call people, and nobody legitimate needs your Medicare number, Social Security number or bank details from an unexpected phone call.
If you are unsure whether a call was real, you are welcome to ring us and read us what they said.
Yes. A Supplement pays gaps in Original Medicare and does not include prescription coverage. If you go with Original Medicare plus a Supplement and add no drug plan, you start a 63-day count that leads to a permanent Part D penalty.
Nothing. We are paid by the insurer if you enroll, and your premium is exactly the same whether you use a broker or sign up on your own. There is no fee and nothing is added to what you pay for the plan.
Ask us what any specific plan pays us and we will tell you the number.
Keep reading
Two practical things to do before your first appointment, and one that has nothing to do with Medicare at all.
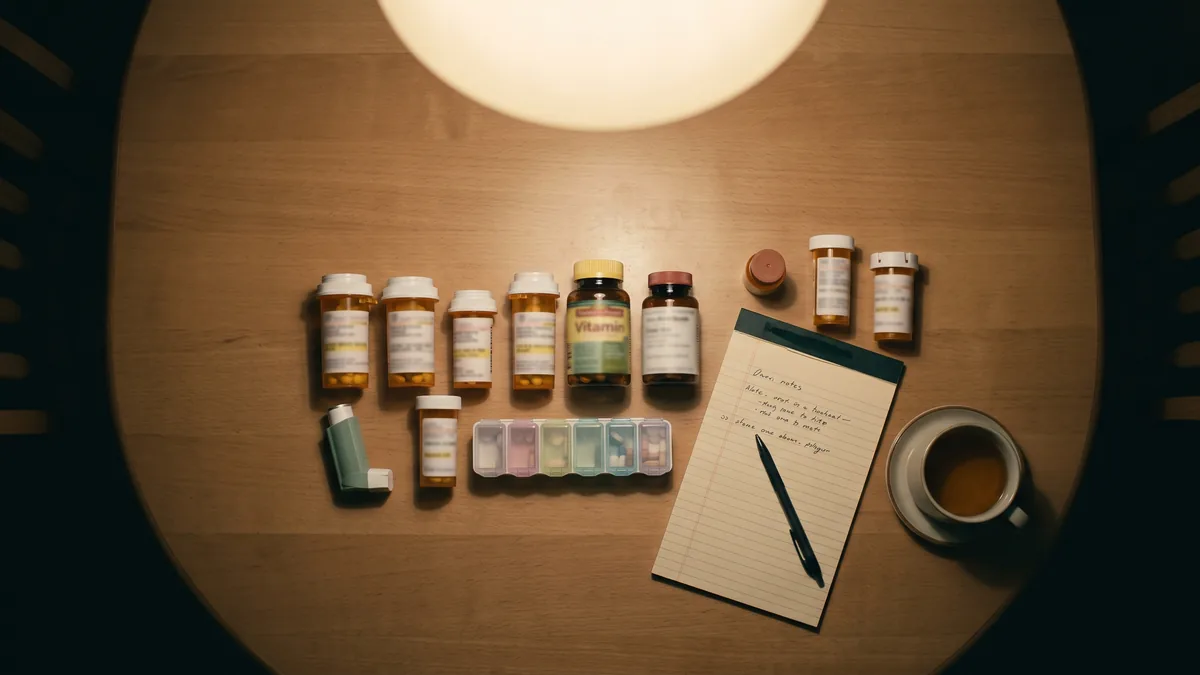
The seven things to write down per medication, the four categories people always leave off, and how to build a working list in twenty minutes at your kitchen table.
Read the article
Medication synchronization, a review of the whole list at once, easier packaging, inhaler technique, safe disposal, your fill history, and the two assistance programs most people never hear about.
Read the article
Courts, drop-in times, beginner clinics and age-based rec passes in Greeley, Windsor, Loveland, Fort Collins, Eaton, Johnstown and Wellington, plus the medication question a pharmacist would ask before your first hot Saturday.
Read the articleNorthern Colorado Medicare help
One appointment. Advantage, Supplement and Part D side by side, your medications priced for the full year, your doctors checked against each plan's network, and the extra benefits confirmed rather than assumed. No pitch waiting at the end of it.
Ask us what a plan pays us and we will tell you the number. Haven is paid by the insurer if you enroll, and your premium is the same whether you use a broker or enroll directly.